Personal loan · Unsecured
A personal loan, sized to what you can repay.
We arrange unsecured financing for salaried and self-employed applicants with documented income, with a tenure matched to affordability and one consolidated document pack for the bank.
Unsecured financing, prepared properly
A personal loan is unsecured: no property or vehicle is pledged, so the bank relies on your income, existing commitments and repayment history. Banks quote personal loans in different ways, some at a flat rate and some on a reducing balance, and each bank sets its own minimum income and eligibility rules.
Because there is no collateral, how your case is presented matters. We help you work out an amount and tenure that keep your total commitments manageable, check that your payslips, bank statements or business records support your declared income, and put everything into one consolidated pack before it goes to the bank.
We are a consultancy, not a lender. The bank decides whether to approve your application, the amount and the rate.
Who it suits
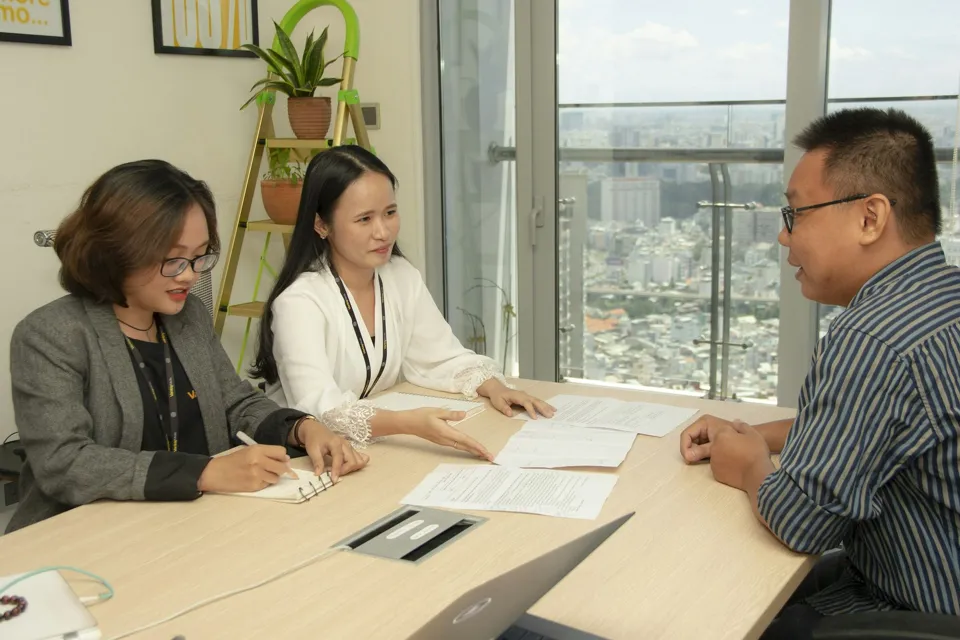
Personal financing suits applicants with documented, verifiable income and a clear plan for the funds.
- Salaried employees with payslips and EPF contributions
- Commission earners with a steady track record
- Self-employed applicants with SSM registration and tax returns
- Borrowers consolidating smaller debts into one instalment
What we handle
We focus on the details that most often hold a personal loan back: income evidence, commitments and a realistic amount.
Amount sized to affordability
We work out an amount and tenure that keep your total monthly commitments manageable, based on your actual income.
Income evidenced clearly
Salary, commission or business income is documented the way banks expect, which is where many personal loan cases fall short.
One consolidated pack
Your documents are checked and assembled into one complete pack, so the bank does not need to keep asking for more.
An honest view before applying
If your commitments or credit records make approval unlikely right now, we tell you, rather than submit and hope.
How a personal loan application works
Four steps, from your first enquiry to the funds reaching your account.
-
01
Consultation
We discuss what the loan is for, your income type and existing commitments, and agree a realistic amount and tenure.
-
02
Document review
We check your payslips, bank statements or business records and assemble them into one complete pack.
-
03
Bank submission
We submit to the partner bank whose income and eligibility criteria best match your profile and track the case.
-
04
Offer and disbursement
We walk you through the offer, the rate and conditions. Once you accept, the bank disburses the funds to your account.
Documents checklist
Personal Loan
Typical requirements. Individual banks may ask for more depending on your profile.
Salaried
- MyKad (front and back)
- Latest 3 months salary slips
- Latest 3 months bank statements
- EPF statement or EA form
Self-employed
- MyKad (front and back)
- SSM business registration
- Latest 6 months business bank statements
- Latest tax return (Form B) and receipt
Estimate your instalment
This estimate uses a reducing balance. Banks quote personal loans in different ways, so ask which method a quoted rate uses.
Indicative placeholder rate — not a quotation.
Estimated monthly instalment
RM 966.64
- Total payable
- RM 57,998.40
- Method
- Reducing balance
Estimate only. Actual rate and approval are subject to the bank's assessment.
Personal loan questions
What is the minimum income for a personal loan?
Each bank sets its own minimum monthly income, and the figure often differs for salaried and self-employed applicants. We will tell you which partner banks are realistic for your income level.
Do I need a guarantor or collateral?
No collateral is needed, because a personal loan is unsecured. Banks rely on your income, commitments and credit records instead. A guarantor is not usually required, although a bank may ask for one in some cases.
How do banks assess my debt service ratio?
Banks compare your total monthly commitments, including the new instalment, with your net income. Each bank sets its own limit. We work out your position before submission so the amount you request is realistic.
Can self-employed applicants apply?
Yes. Banks usually ask for SSM registration, business bank statements and your latest tax return (Form B) with proof of payment, so your income can be verified.
Other financing routes
Check your eligibility
Tell us about your income and what the loan is for, and a consultant will review which partner banks fit your profile.
- No fees are charged to submit an enquiry. Approval and final terms remain entirely with the bank.
Enquiry received
A consultant will contact you on your preferred channel within one working day. Nothing has been submitted to any bank yet.